
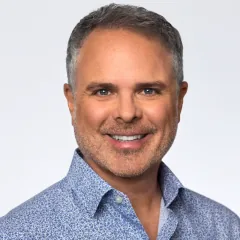
CJ Kerls
Branch Manager / SVP of Mortgage Lending · NMLS #243438
VA Loans in the Bay Area and Sonoma County
Zero down up to $2 million, no monthly mortgage insurance and no lender fees. Yes, even at Bay Area prices.
Your VA benefit goes further than you think
Most veterans I talk to in California were told, somewhere along the way, that their VA benefit wouldn't stretch to Bay Area prices. It does. I'm CJ Kerls, Branch Manager and SVP of Mortgage Lending at Rate, and in 35+ years of lending I've learned that the right answer usually depends on the lender knowing the program. Through Rate, I offer the full range of VA loans, up to $3 million, with no lender fees, for buyers across the Bay Area, Sonoma County and Southern California.
VA loan basics
What is a VA Loan?
A VA loan is a mortgage from a private lender that is partly guaranteed by the U.S. Department of Veterans Affairs. That guarantee is what lets lenders offer zero down payment, no monthly mortgage insurance, and pricing that is usually better than conventional financing.
Here's what I see most often in California. Veterans assume the VA benefit tops out somewhere below Bay Area prices, so they never ask. They save for years toward 20 percent down on a conventional loan when they could have bought with nothing down. If you have your full entitlement, the VA sets no loan limit, and I can lend up to $2 million with no down payment and no monthly mortgage insurance.
01
VA basics and eligibility
Who is eligible for a VA loan?
Veterans, active-duty service members, members of the National Guard and Reserves who meet the service requirements, and some surviving spouses. Eligibility depends on your length and type of service and your discharge. The VA confirms it with a Certificate of Eligibility.
What is a Certificate of Eligibility, and how do I get one?
The Certificate of Eligibility, or COE, is the VA's confirmation that you qualify for the benefit. It also shows how much entitlement you have available. You don't have to request it yourself. I can usually pull it directly through the VA's lender portal at the start of your application.
What credit score do I need for a VA loan?
For loan amounts under $2 million, there's no minimum. The VA doesn't set one, and Rate doesn't add one, even when a file is underwritten by hand. For loan amounts of $2 million to $3 million, the minimum is 720.
Your full credit history still matters. Most files go through automated underwriting. Lower scores or recent late payments can mean the loan is reviewed by hand, which takes more documentation but is still a path to approval.
Is the VA loan a one-time benefit?
No. You can use it again and again over your lifetime, and in some cases you can hold more than one VA loan at the same time. When you sell a home and pay off its VA loan, that entitlement is generally restored for your next purchase.
Why would one lender turn down a VA loan that another approves?
The VA publishes its guidelines, but lenders are allowed to stack their own stricter rules on top. These are called overlays. A lender might cap debt-to-income at a set number or require a minimum score the VA doesn't. If you've been turned down, it's worth finding out whether the "no" came from the VA's rules or from that lender's.
02
How much you can borrow, and when county limits matter
Is there a maximum loan amount on a VA loan?
The VA doesn't set one if you have your full entitlement. It stopped applying loan limits to those borrowers in 2020. Each lender sets its own maximum, and here's mine:
- Up to $2 million: zero down
- $2 million to $3 million: 10 percent down, but only on the amount above $2 million
- Maximum loan amount: $3 million
- Minimum credit score of 720 for loan amounts of $2 million and up
That 10 percent is figured on the part above $2 million, not the whole price. On a $2.1 million purchase, that works out to roughly $10,000 down. On a $3 million purchase, it's $100,000.
The thresholds are based on the loan amount, and a funding fee rolled into the loan counts toward it. If you're exempt from the fee, the price and the loan amount line up. If you're not, I'll show you exactly where the zero-down cutoff falls for your purchase.
Either way, that's zero down well above the Bay Area's $1,249,125 conforming limit. You still qualify on income, credit and the property, and a bigger loan means a bigger payment to qualify for.
What does "full entitlement" mean?
In plain terms, you have full entitlement if you don't have an active VA loan on another property and you haven't lost entitlement through a VA loan that ended in foreclosure or a short sale. Most veterans buying their first home with the benefit have full entitlement.
When do county loan limits matter?
Only when part of your entitlement is still tied up, usually because you kept a home with a VA loan on it and rented it out. In that case, the county's conforming loan limit sets how much you can borrow with zero down. Above that, you'd need a down payment.
The limit depends on where you buy. In 2026 it's $1,249,125 in San Francisco, San Mateo, Santa Clara, Alameda, Contra Costa and Marin counties, and $897,000 in Sonoma County. Southern California counties, including Riverside County for Palm Springs, have limits of their own.
How do I find out how much I can borrow with partial entitlement?
Your lender calculates it from your COE and the county limit where you're buying. This should happen at preapproval, not at the end. If it's skipped, a buyer can learn just before closing that they need to bring a down payment they didn't plan for.
Bought a home with VA before?
Whether you still own it or sold it years ago can change what you can borrow today. Bring your COE and I'll work out your remaining entitlement before you write an offer.
03
What a VA loan costs
2026 VA funding fee, purchase loans
The funding fee is a one-time charge, figured as a percentage of the loan amount. Most borrowers roll it into the loan.
| Down payment | First use | After first use |
|---|---|---|
| Less than 5% | 2.15% | 3.3% |
| 5% or more | 1.5% | 1.5% |
| 10% or more | 1.25% | 1.25% |
Veterans who receive VA compensation for a service-connected disability don't pay the funding fee.
A few other groups are exempt too. Source: U.S. Department of Veterans Affairs, rates effective April 7, 2023.
Does a VA loan have mortgage insurance?
No, and that's one of the biggest savings in the program. A conventional loan with less than 20 percent down carries monthly private mortgage insurance until you build enough equity. An FHA loan charges an upfront premium plus a monthly premium, often for the life of the loan. Most jumbo loans skip mortgage insurance but typically require 10 to 20 percent down. A VA loan has neither monthly mortgage insurance nor a required down payment. The one-time funding fee, covered next, is the only government charge, and many veterans are exempt from it.
What is the VA funding fee?
A one-time fee paid to the VA that helps keep the program running without down payments or monthly mortgage insurance. It's a percentage of your loan amount, set by the type of loan, whether you've used the benefit before, and your down payment. See the table above for purchase loans. On a purchase, the funding fee is the one cost you're allowed to finance into the loan.
Who doesn't pay the funding fee?
You're exempt if any of these apply:
- You receive VA compensation for a service-connected disability
- You're eligible for that compensation but receive retirement or active-duty pay instead
- You're a surviving spouse receiving Dependency and Indemnity Compensation
- You're a service member with a proposed or memorandum rating before closing that says you're eligible for compensation
- You're on active duty and show proof of a Purple Heart on or before closing
I don't have a disability rating. Should I check whether I qualify?
Yes, before you buy. Many veterans never file a claim because they assume their condition is too minor. Compensation starts at a 10 percent rating, and common service-connected conditions like hearing loss and tinnitus can qualify. Any rating that comes with VA compensation removes the funding fee, on this loan and on future VA loans, while you receive it. On a $1 million zero-down purchase, that's $21,500 saved the first time and $33,000 on a later use.
Timing matters. If your rating is in place before closing, you skip the fee. If it comes after closing, you may still get a refund, but only if the VA makes the compensation retroactive to a date before your closing. If you think you may qualify, start the claim early, and tell me so we can plan the closing around it.
Can I put money down to lower the fee?
Yes. Putting 5 percent down lowers the fee to 1.5 percent, and 10 percent down lowers it to 1.25 percent, whether it's your first VA loan or a later one. If you plan to buy more than once with the benefit, it can make sense to save toward 5 percent for the second purchase, which cuts the subsequent-use fee from 3.3 percent to 1.5 percent.
Is a VA loan really zero cost to close?
Zero down isn't zero cost. You'll still have the appraisal, title and escrow fees, prepaid property taxes and insurance, and your own home inspection, which I always recommend. On a purchase, those costs can't be rolled into the loan. They can be covered by the seller, though, and I'll show you how below.
Do you charge lender fees on VA loans?
No. I don't charge lender fees on VA loans. You'll still have third-party costs like the appraisal, title and escrow, but no origination fee or lender fee from me.
How much can a seller contribute?
The VA puts no cap on seller credits toward normal closing costs. On top of that, the seller can contribute concessions of up to 4 percent of the home's reasonable value. Concessions can pay your funding fee, prepay your homeowners insurance, or pay off existing debt such as a car loan or credit card balance. Paying off a debt can lower your monthly obligations and help you qualify. Concessions can't be taken as cash.
Can I be responsible for my buyer's agent's commission?
Yes, and this catches people off guard. Since late 2024, VA buyers can pay their own agent's commission. If your buyer agreement promises your agent more than the seller agrees to pay, the difference can come out of your pocket at closing. Read the agreement before you sign it, and send me a copy when we set up your loan so we can plan for it.
04
Buying with a VA loan
Can a VA offer compete in the Bay Area?
Yes, when it's set up right. Some listing agents still believe a VA loan can't handle a high price or a fast close, and that belief costs veterans homes. A full underwrite before you shop, the appraisal ordered on day one, and a call from your lender to the listing agent to answer questions directly go a long way. When I hear a listing agent say a property "won't go VA," I'd rather call and find out the actual concern than let the offer get set aside.
How long does a VA loan take to close?
With the appraisal ordered right away, a VA purchase can close on the same kind of timeline as a conventional loan, often in under 30 days. VA loans get a reputation for being slow when the lender orders the appraisal late or doesn't know the program.
Is the VA appraisal the same as a home inspection?
No. A VA-assigned appraiser confirms the home's value and checks the VA's minimum property requirements, basic safety and soundness items. It isn't a full inspection, and there's no such thing as a VA inspector. Hire your own home inspector, and in older Bay Area homes, consider a sewer lateral inspection too.
Can I buy a duplex, triplex or fourplex with a VA loan?
Yes, with zero down, as long as you live in one of the units as your primary home. Rent from the other units can count toward qualifying, but only if you meet the reserve requirements and have landlord experience or a property manager in place. Without those, you qualify on your own income. In San Francisco, where two- to four-unit buildings are common, this is one of the most useful features of the program.
Can I use a VA loan to buy a second home or vacation home?
No. A VA loan is for the home you live in. That matters in Sonoma County and Palm Springs, where many buyers are shopping for a weekend place. If the Healdsburg cottage or the Palm Springs condo will be your primary residence, VA can work. If it's a second home, we'd look at other financing.
Do I have to live in the home forever?
No. You need to intend to move in and make it your primary residence; the common expectation is about a year. After that, you can move out and rent the home without refinancing out of the VA loan. You can also rent spare rooms to roommates from day one, since you're still living there. What you can't do is buy with a VA loan while planning from the start to rent the whole home out.
Can I buy a condo with a VA loan?
Yes, if the condo project meets VA requirements. I'll check the building's status early so a condo issue doesn't surface after you're in contract.
05
Refinancing a VA loan
What is a VA IRRRL?
The Interest Rate Reduction Refinance Loan, often called a VA streamline, refinances an existing VA loan into a lower rate. In most cases it doesn't require an appraisal or income documentation, and the funding fee is 0.5 percent. It's the simplest refinance in the mortgage business, but it still has to make sense. Your current loan needs about six months of payments behind it, and the VA requires the closing costs to be recouped through the lower payment within 36 months. If you plan to move before you'd break even, it isn't worth doing.
How does a VA cash-out refinance work?
A VA cash-out refinance replaces your current mortgage, VA or not, with a new VA loan and pays you the difference in cash. It can go up to 100 percent of the home's appraised value. It's handled much like a purchase: full appraisal, full income and asset documentation, and the home has to be your primary residence.
What is the funding fee on a VA cash-out refinance?
2.15 percent the first time you use your VA benefit and 3.3 percent after that, unless you're exempt. On a $1 million loan, that's $21,500 or $33,000.
When is a conventional loan or a HELOC better than a VA cash-out?
If you don't have a disability exemption and you'll still have meaningful equity after the cash-out, roughly under 80 percent loan-to-value, a conventional cash-out refinance can cost less overall, even at a slightly higher rate. And if you only need a modest amount, a HELOC lets you keep your current low rate and skip the funding fee entirely. I'll run the numbers on each before you choose. I'd also caution against pulling out every dollar of equity just because the program allows it. Equity is what gives you options if you need to sell.
06
Renovation and energy-efficient upgrades
Can I buy a fixer-upper with a VA loan?
Yes. A VA renovation loan combines the purchase price and the cost of improvements into one loan with one monthly payment. The loan is based on the home's as-completed value, so the appraiser values the home as it will be after the work is done. You'll need a VA-registered contractor to bid the project, and the work has to be planned and priced before closing.
Can I finance energy-efficient improvements?
Yes, through a VA Energy Efficient Mortgage, available on a purchase or a refinance. It adds the cost of upgrades such as insulation, new windows or a solar water heater to your loan. You'll need an energy audit or a Home Energy Rating System (HERS) report and contractor bids. For projects between $3,000 and $6,000, the lender has to confirm the expected utility savings justify the higher payment.
The figures on this page describe VA program guidelines and general market practice. They are not terms offered to any particular borrower, not a quote, and not a commitment to lend. Loan approval is subject to credit and underwriting review, and not all applicants will qualify. Funding fee rates are set by the U.S. Department of Veterans Affairs and are subject to change. Rate is a private corporation and is not affiliated with the U.S. Department of Veterans Affairs or any other government agency. This content is for informational purposes only and does not constitute legal, tax, or financial advice. Consult a qualified professional. CJ Kerls, NMLS #243438 | CA DRE #01320626.